A Debt of Courtesy: How a Local Firm Settles a Customer’s Final Account
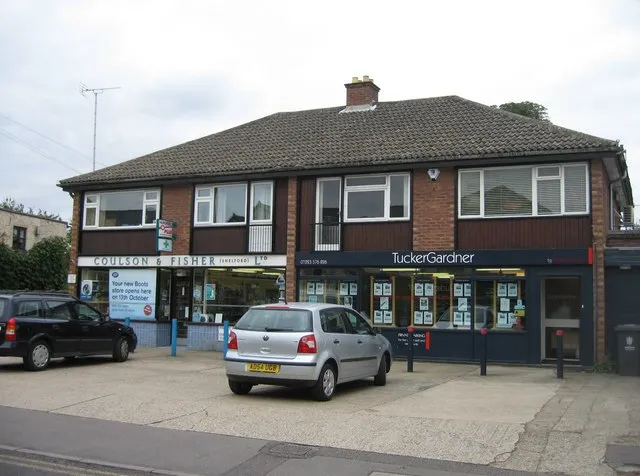
Photo: Sebastian Ballard, CC BY-SA 2.0, via Wikimedia Commons
In 2026, much of business runs on reminders: automated statements, scheduled calls, standing letters that arrive because a date has come round. For most of the year this is a virtue. It keeps the order book honest and the accounts tidy. But when a customer dies, routine must give way to judgement. The final account is not simply a balance to be collected. It is the last piece of business a family firm will transact with that name, and it should be handled as such.
A customer of thirty years is not a line in a database. They are a set of habits, a history of instructions, perhaps a key that was never returned and a tea order that was always the same. The firm’s duty is to close the account properly. The firm’s character is revealed in how it does so.
Stop the Routine Before It Causes Harm
The first practical step is to pause the machinery. Automated invoices, statements, reminders and marketing mail should be suppressed as soon as the firm is satisfied that the customer has died. A letter addressed to the deceased, demanding payment or offering a seasonal promotion, causes unnecessary distress and makes the firm look careless.
This does not mean cancelling direct debits or closing accounts unilaterally. Those steps may belong to the executor or the bank. It means placing a clear note on the account, assigning one named person to deal with it, and preventing multiple members of staff from telephoning the family with different questions. In a small firm, everyone knows the customer. That is an advantage, but only if the knowledge is coordinated.
Establish the Right Point of Contact
Ask, gently, who is dealing with the customer’s affairs. It may be a family member, a solicitor, or an executor who has not yet been confirmed. Do not demand a death certificate in the first telephone call. Record what you have been told, by whom, and on what date. If authority is not yet clear, correspond with the person the family has nominated and keep the language neutral.
Confidentiality still applies after death. Information should be shared only with those entitled to receive it. A family firm’s reputation for discretion is built in moments like these, when gossip is tempting and restraint is required.
Give the Executor a Clear Statement, Not a Demand
When the time comes, provide a final statement of account in plain language. Show invoices, payments, credit balances, deposits and any outstanding amounts. If the estate is awaiting probate, say so plainly and confirm that the firm is not pressing for immediate payment. A statement that reads like a threat is not a courtesy; it is an unnecessary burden.
Where a solicitor is acting, deal with the solicitor. Where the family is acting, deal with the family. Avoid adding late-payment charges or interest during the initial bereavement period unless there is a clear commercial reason and the matter has been reviewed by a partner or proprietor. A small balance can be written off; a large one may need respectful recovery. The policy should be settled before the telephone rings, not improvised in the moment.
Return What Was Never Ours
Many long-standing accounts involve property: keys, documents, drawings, samples, equipment, patterns or stock held for a customer. These should be returned promptly and recorded. Prepare a simple inventory, arrange collection at a time that suits the family, and obtain a signature. Do not dispose of anything because it seems unimportant. What looks like clutter to the firm may be a piece of family history.
Confidential papers should be returned or destroyed securely, according to instruction. The firm should keep its own records for the required period, but it should not retain a customer’s private correspondence simply because it is convenient.
The Letter That Is Not an Invoice
A condolence letter should be sent separately from any financial correspondence. It should be on plain paper, signed by a named person, and free of balance statements, account numbers and payment requests. It need not be long. It should not be a template beginning “Dear Customer”. If there is a genuine memory to mention, mention it. If there is not, a short expression of sympathy and an offer of practical help is enough.
The letter should say who to contact and assure the family that there is no hurry. It should not pretend that the firm knew the deceased better than it did. Sincerity is more valuable than polished wording.
Make the Policy Before the Phone Call
A family firm cannot rely on good instincts alone. It should have a written procedure for bereavement: who takes the call, who pauses the account, who approves a write-off, how property is returned and how records are closed. The policy should be applied consistently, not according to the size of the balance or the prominence of the family.
Generosity should not be careless. A firm can write off a modest sum as a matter of courtesy and still recover a substantial debt through the executor. What matters is that the decision is recorded, explained and reviewed. The ledger should not become a place for private sympathy to turn into public muddle.
Close the File, Keep the Memory
When the account is settled, mark the file clearly as closed following bereavement. Retain the records for the statutory period. Send the executor a brief note of confirmation and thanks. Remove the name from mailing lists. Debrief the staff who dealt with the matter, not to apportion blame but to learn what could be done better next time.
A mission statement can be printed and framed. The final account cannot. It is written in letters, telephone calls, returned keys and the decision not to send a reminder. For a firm that has traded since 1946, that is the more honest record of what it believes.